
Self-insured plan sponsors can satisfy their compliance obligations by completing and filing Form 720, with its accompanying 720-V payment voucher. Although Form 720 is a quarterly return, for PCORI, Form 720 is filed only annually by July 31. The form is available here, and the PCORI fee reporting can be found in Part II, Line 133. Plan sponsors of self-insured health plans and health insurers must pay fees equal to the applicable fee times the average number of covered lives. Plan sponsors cannot pay these fees via the plan or with plan assets.
The applicable fee per covered life is determined by the end of the plan year:
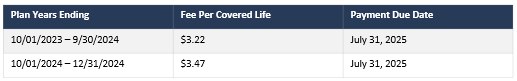
There are three methods for calculating the average number of covered lives, including the Actual Count Method, Snapshot Method, and 5500 Method. The IRS has issued detailed guidance on the multiple methods that can be used to calculate the PCORI fee. As a reminder, covered lives include spouses, dependents, retirees, and COBRA beneficiaries.
If a plan sponsor offers a stand-alone HRA, one of the methods must be used to count the average number of covered lives. If the HRA is integrated with an insured plan, the plan sponsor will be responsible for a separate PCORI fee on the HRA-covered lives, even though the insurer will pay for the covered lives under the insured plan. Plan sponsors of an HRA integrated with a non-account self-insured plan will not have to pay separately for the self-insured plan and HRA.